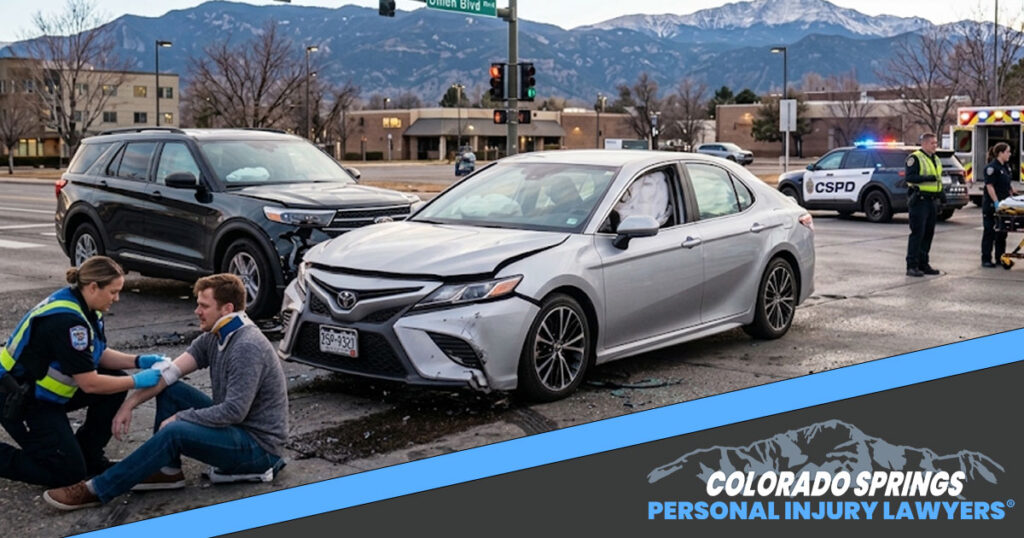
Picture this. You are driving home in Colorado Springs when a distracted driver runs a red light and hits you hard. Your car spins, airbags deploy, and an ambulance ride follows. Suddenly, Colorado minimum insurance becomes more than a legal requirement. It becomes a question of whether the available coverage can actually pay for your losses.
That raises the next question: is Colorado minimum insurance enough after a serious Colorado accident?
The answer matters most when a crash causes serious injuries, involves several vehicles, or includes an uninsured or underinsured driver. In those situations, minimum policy limits may not go very far, and a Colorado Springs car accident lawyer can help identify other coverage that may apply.
Colorado Minimum Insurance Requirements: The Limits You Must Carry
Colorado requires liability insurance for drivers, and the same basic requirements apply to motorcycles as well. However, knowing the numbers is only the first step.
Here are the Colorado minimum insurance limits you must carry, often written as 25/50/15:
- Bodily Injury Liability – $25,000 per person
- Bodily Injury Liability – $50,000 per accident
- Property Damage Liability – $15,000 per accident
Because these are the Colorado minimum insurance limits, they are common. However, common does not mean sufficient after a serious crash.
What Colorado Minimum Insurance Does Not Cover
Many people miss the biggest limitation of Colorado minimum insurance. The required bodily injury limits may satisfy state law, but they can be exhausted quickly after a serious accident.
Colorado requires at least $25,000 in bodily injury liability coverage for one injured person and $50,000 per accident when multiple people are injured. That money may have to cover far more than the initial emergency room bill.
Serious accident losses can include:
- Imaging and diagnostic testing
- Surgery
- Physical therapy and rehabilitation
- Follow-up and long-term medical care
- Lost income
- Reduced future earning ability
- Traumatic brain injury treatment and monitoring
- Pain and suffering
- Permanent impairment or disability
- Loss of enjoyment of life
Once the at-fault driver’s bodily injury limits are exhausted, their liability insurer generally does not simply keep paying the remaining losses. That is when other sources of coverage, including applicable underinsured motorist coverage, may become important.
UM/UIM coverage can help with bodily injury losses when the at-fault driver has no insurance or does not have enough insurance. It does not generally pay for damage to your vehicle. Collision coverage or other applicable property damage coverage may address those losses. A Colorado Springs car accident lawyer can review the policies involved, determine which coverage may apply, and help protect your claim before you accept a settlement.
Colorado Minimum Insurance vs. Real-World Costs
Even when a driver carries Colorado minimum insurance, the math can still be harsh. Here are a few simple examples.
For example, a rear-end crash leads to neck pain. At first, it looks like whiplash. Next, an MRI shows a herniated disc. Then you have injections, physical therapy, and time off work. A modest care path can reach $30,000 or more. If the at-fault driver has Colorado minimum insurance, the bodily injury limit could be $25,000 for you. Therefore, the policy can vanish before you feel stable again.
Next, consider property damage. A newer vehicle gets hit and needs a bumper, sensors, lights, and calibration. Then add towing and storage. Even a moderate repair can hit $18,000. However, the Colorado minimum insurance property damage limit is $15,000 per accident. So, you can see the gap right away.
Then, consider multiple injured people. A rideshare car carries three passengers. A crash injures all three. The at-fault driver has Colorado minimum insurance with a $50,000 per accident bodily injury cap. If each passenger has a serious claim, that cap can split fast. As a result, each person may receive far less than their actual damages.
Supplementary Coverage Options That Help When Colorado Minimum Insurance Falls Short
You cannot control how much insurance another driver carries, but you can choose the protection on your own policy. Because Colorado minimum insurance can leave major gaps after a serious crash, additional coverage may matter.
Important options include:
- Uninsured and underinsured motorist coverage: Uninsured motorist coverage and underinsured motorist coverage in Colorado may help when the at-fault driver has no insurance or not enough coverage. If the other driver carries only Colorado minimum insurance, UIM coverage may help cover losses that exceed those limits.
- Medical Payments Coverage (MedPay): MedPay can help with accident-related medical expenses, including deductibles, co-pays, and early treatment costs. It may apply regardless of who caused the crash.
- Comprehensive and collision coverage: These cover damage to your vehicle rather than injuries or pain and suffering. They may help repair or replace your car sooner while the liability claim is still being resolved.
Review Your Coverage Before You Need It
Minimum limits may satisfy Colorado law, but they may not be enough after a serious accident. Reviewing your own policy before a crash can help you understand where gaps may exist.
If you were injured and the at-fault driver only carried Colorado minimum insurance, speak with a Colorado Springs car accident lawyer about the coverage that may apply.
Why a Colorado Springs Car Accident Lawyer Matters in a UM/UIM Claim
When the at-fault driver has no insurance or too little coverage, a UM/UIM claim may become an important source of compensation. Even though the claim may involve your own insurer, that does not mean the process is simple.
A Colorado Springs car accident lawyer can help:
- Confirm the available coverage under your policy and the at-fault driver’s policy.
- Document your losses, including medical expenses, lost income, and future care needs.
- Handle communications with the insurer and present evidence supporting the value of your claim.
- Review settlement terms and releases before you sign anything that could affect additional coverage.
- Address disputes with your insurer if there is disagreement about coverage or the value of your losses.
Timing can also matter. Some policies contain requirements that affect how and when you resolve the claim against the at-fault driver. Signing a settlement or release too early could create problems for a later UM/UIM claim.
For that reason, it can be especially important to speak with a Colorado Springs car accident lawyer before accepting a policy-limits settlement or resolving a claim involving an uninsured or underinsured driver.
What To Do After an Accident in Colorado
The steps you take after a serious crash can affect both your health and your insurance claim.
After a Colorado Springs car accident:
- Call 911 and get medical care: Even if you feel okay, get checked and follow your treatment plan.
- Document the scene: Take photos of the vehicles, license plates, road conditions, and visible injuries.
- Get witness information: Ask for names and contact details when possible.
- Collect the other driver’s information: Get their name, license, registration, and insurance information.
- Get the police report details: Ask how and when you can obtain a copy.
- Notify your insurer promptly: Let them know the other driver may be uninsured or underinsured.
- Be careful with recorded statements: Do not guess about what happened or minimize your injuries before you understand the insurance issues.
- Contact a Colorado Springs car accident lawyer: An attorney can review the available policies, identify coverage gaps, and explain what options may still be available.
If the other driver carries only Colorado minimum insurance, those limits may not cover all of your losses after a serious crash. This is why it is important to contact a Colorado Springs car accident attorney before signing a release or accepting a settlement that could limit your recovery.
FAQs (Frequently Asked Questions)
What are the Colorado minimum insurance requirements for drivers?
Colorado requires at least $25,000 in bodily injury coverage per person. Drivers also need $50,000 per accident for bodily injury and $15,000 for property damage. These are minimum liability limits.
Is Colorado minimum insurance enough after a serious car accident?
It may not be. A serious injury can create medical bills, lost income, future treatment costs, and other damages. Those losses can quickly exceed a $25,000 bodily injury limit. Multiple injured people may also have to share the $50,000 per-accident limit.
What does Colorado minimum insurance cover?
Minimum liability insurance pays for injuries and property damage you cause to others, up to the policy limits. It does not automatically cover your own injuries or vehicle damage. Separate coverage may apply to those losses.
How can UM/UIM coverage help after a Colorado accident?
UM/UIM coverage may help when the at-fault driver has no insurance or too little insurance. It can apply to bodily injury losses that exceed the other driver’s available coverage. That may include medical expenses, lost income, pain and suffering, and future care.
How does a UM/UIM claim work when the other driver has too little insurance?
A UM/UIM claim is generally made through your own insurer. The insurer reviews fault, damages, and the coverage available from the at-fault driver. Because settlement terms and policy requirements can affect the claim, a Colorado Springs car accident lawyer can review the coverage before you sign a release.
Is the Insurance Enough to Cover Your Colorado Springs Accident?
If your injuries are serious and the available insurance looks too small to cover your losses, the decisions you make next can matter. Medical bills, lost income, future treatment, and pain and suffering can quickly exceed minimum policy limits.
A Colorado Springs personal injury lawyer can review the policies involved, identify additional sources of compensation, and handle the insurance companies on your behalf. That can be especially important when UM/UIM coverage or multiple policies may apply.
Do not assume the first policy limit is the end of the road. At Colorado Springs Personal Injury Lawyers®, we can look for additional coverage and help you understand what compensation may still be available.
Request a free consultation before you accept a settlement that may not cover the full cost of your injuries.